Payday Super Is Now Law: What Employers Need to Know

Payday Super Is Now Law: What Employers Need to Know

Payday Super is Now Law: What Employers Need to Know
Tax time with wooden alphabet blocks, red alarm clock, calculator and pen on 1040 tax form background

Payday Super changes how and when you pay Super to employees.

With the new changes coming into effect, Super must now be paid at the same time as wages, regardless of whether you run payroll weekly, fortnightly, or monthly.

Programs such as Xero, have a feature allowing you to streamline this process to ensure compliance.

To avoid falling foul of the new compliance rules, super contributions must reach your employee’s super fund within 7 days from their pay day.

As funds can take time to process payments (and with the usual banking delays), we recommend payments should be made on the same day that wages are paid.
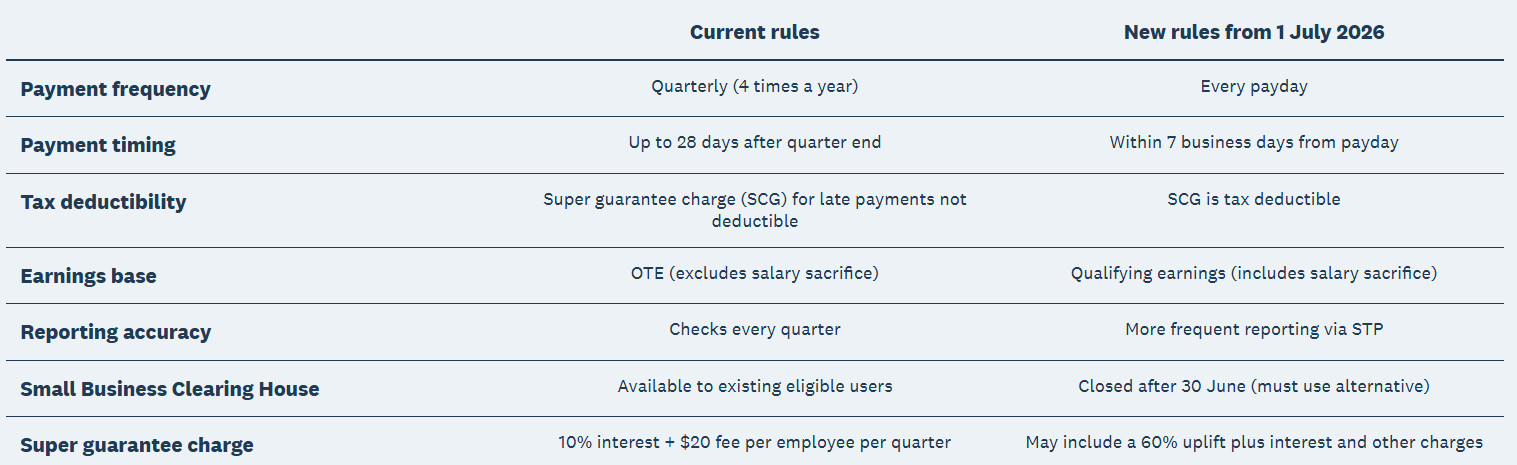
Reporting of superannuation payments will now be included as part of your STP (Single Touch Payroll).

This means the ATO will have greater visibility & data matching ability to check compliance.

From 1 July 2026

The super guarantee charge applies when amounts aren’t received by a super fund within 7 business days after payday (unless longer applies, such as for new employees).

The super guarantee charge:

  • is assessed by the ATO (employers don’t lodge a super guarantee statement)
  • is calculated based on qualifying earnings
  • includes interest that compounds daily at the general interest charge rate
  • includes an amount to reflect the cost of enforcement and encourage early disclosure by employers – this is called the administrative uplift amount. It can be reduced if the ATO hasn’t taken action in the past and if the employer lodges a voluntary disclosure statement
  • is tax deductible.

If you have any questions, please reach out to your Accountant.

Open Hours

Monday to Friday
8:00am to 5:00pm

Closed Public Holidays

Contact Us

27 Welsford Street
Shepparton, VIC 3630

T: (03) 5833 3000
F: (03) 5831 2988
Email Us

Anti Money Laundering & Counter Terrorism Financing Laws

Anti Money Laundering & Counter Terrorism Financing Laws

Anti Money Laundering & Counter Terrorism Financing Laws

Tax time with wooden alphabet blocks, red alarm clock, calculator and pen on 1040 tax form background

From 1 July 2026, the new Australian anti money laundering and counter terrorism financing (AML/CTF) regime will apply to accounting firms, real estate agents and law firms, including us.

Accountants often act as “trusted gatekeepers” because they help set up corporate structures, manage trusts, and facilitate transactions. To prevent criminals from exploiting this, accountants are classified as reporting entities if they provide any of the following “designated services”:

  • Assisting with the sale or purchase of an entity or business
  • Assisting with the creation, operation, or restructuring of an entity (like a company or trust)
  • Acting as (or arranging for someone to act as) a director, secretary, trustee, or nominee shareholder
  • Dealing with money or property on behalf of a client

General tax preparation, tax planning, bookkeeping and general business advice are excluded and not considered a designated service.

What we are required to do:

We are required to undertake identity checks, understand your request and its purpose, and assess the risk of money laundering and other financial crime before we undertake the work for you.

What does this mean for you?

A key change is that we are required to start asking you for more information. Depending on your structure, this will include information about:

  • your identity and the identity of beneficial owners; and
  • who owns and controls you. We may also have to ask for documents related to this, like your constitution or trust deeds.

In some cases, we will be required to ask how the transaction will be funded and about your source of wealth.

We are required to keep this information up-to-date and continue to monitor the risk of money laundering and other financial crime as specific services are requested.

Your information

We will use a secure electronic platform to collect and verify your identity. By using this secure platform, your identity documents are not physically retained in our client files.

We are aiming to keep this process as efficient and streamlined as possible for you. Please understand that processing times may be impacted by any delays in providing the relevant identity check or additional information requested.

If you have any questions, please reach out to your Accountant.

Open Hours

Monday to Friday
8:00am to 5:00pm

Closed Public Holidays

Contact Us

27 Welsford Street
Shepparton, VIC 3630

T: (03) 5833 3000
F: (03) 5831 2988
Email Us

Minimum Wage & Award Rates Increase from 1 July 2026

Minimum Wage & Award Rates Increase from 1 July 2026

Minimum Wage & Award Rates Increase from 1 July 2026

Tax time with wooden alphabet blocks, red alarm clock, calculator and pen on 1040 tax form background

Most employees are covered by an award. Awards are legal documents that outline minimum pay rates and conditions of employment in an industry or occupation.

The Fairwork Commission has announced a 4.75% increase to minimum wages, provided that:

  • the lowest rate in any award that applies to ongoing employment must be at least $1004.90 per week or $26.44 per hour
  • This increase will apply from the first full pay period starting on or after 1 July 2026. This means the start date & finish date for the period must be in July ie pay period is 1.7 – 7.7.26, paid on 8.7.26
  • if you’re covered by an enterprise agreement, the minimum wage increase may apply. This is because the base pay rate in an enterprise agreement can’t be less than the base pay rate in the relevant award.

To check out your specific award rates click here

It is wise to check other award entitlements such as allowances and deductions as these amounts may have also changed.

For those employees who aren’t covered by an award or enterprise agreement, from 1 July 2026, the National Minimum Wage will be:

  • $1004.90 per week, or
  • $26.44 per hour.

Super remains unchanged at 12%, but is now payable each week when your employees are paid. For further assistance please contact your account.

Finally, new tax scales apply for the payg withholding from employee pays.

These apply strictly for any payments paid on or after 1 July 2026. Most accounting systems will automatically pick up these changes but a census check to confirm this is wise.

Open Hours

Monday to Friday
8:00am to 5:00pm

Closed Public Holidays

Contact Us

27 Welsford Street
Shepparton, VIC 3630

T: (03) 5833 3000
F: (03) 5831 2988
Email Us

Disposing of Property CGT & Reporting

Disposing of Property CGT & Reporting

Disposing of Property – CGT & Reporting

Tax time with wooden alphabet blocks, red alarm clock, calculator and pen on 1040 tax form background

What to know if you’ve disposed of property after 1 July 2025

If you’ve sold, gifted or otherwise disposed of property on or after 1 July 2025, there are a few reporting obligations worth understanding before your tax return is lodged. The ATO has been in touch with taxpayers about these disposals, so here’s a plain-language overview of what it means for you.

What counts as a disposal

A disposal isn’t limited to selling. It also includes gifting property and other similar transactions. If you’ve disposed of property, it’s important to let us know, as it may need to be reported in your return.

Investment property and capital gains tax

An investment property is treated as an asset and is subject to capital gains tax (CGT). Any gains (profits) or losses from a sale or disposal are reported in your tax return. If you record capital losses in the year they occur, they can be used to offset capital gains, both this year and in future years.

Timing matters. A property disposal is reported in the same financial year you enter into the contract, not when settlement occurs.

If the property was your main residence, this needs to be declared, along with your eligibility for the main residence exemption.

Property renovation as a business

Different rules apply if you’re carrying on a business of renovating properties. In that case, your properties are treated as trading stock in the ordinary course of business, your profits are treated as ordinary income, and your losses are deducted in the year they are incurred. These disposals are included in the appropriate section of your tax return.

Keep detailed records for at least five years from the date your return is lodged.

How we can help

We can review your pre-fill information and talk through any property disposal with you. Even where no pre-fill information exists, it’s worth letting us know if you’ve disposed of property, so we can report any capital gain, loss, main residence exemption, other exemption or rollover, or business income relating to the disposal.

Where to get further help

The ATO offers support through several channels, including the Translating and Interpreting Service (13 14 50, 8:00 am to 6:00 pm weekdays), the Indigenous Helpline for First Nations taxpayers (13 10 30), and the National Relay Service at accesshub.gov.au for anyone who is deaf, hard of hearing, or has a speech or communication difficulty. More information is available at ato.gov.au/accessibility.

For a plain-language overview to help avoid common mistakes, you can find the ATO factsheet by searching QC 104431 on the ATO website.

Open Hours

Monday to Friday
8:00am to 5:00pm

Closed Public Holidays

Contact Us

27 Welsford Street
Shepparton, VIC 3630

T: (03) 5833 3000
F: (03) 5831 2988
Email Us

Practice Update July 2026

Practice Update July 2026

Practice Update – July 2026 Edition

Returning to Work


Government’s tax reform package

The Government has recently legislated several of the tax reform measures announced in the 2026 Federal Budget (and in later media releases). These include, among other things:

  • Replacing the CGT discount with cost base indexation and a 30% minimum tax on gains accruing from 1 July 2027 (including gains on pre-CGT assets);
  • Increasing the small business turnover threshold for the 50% active asset reduction from $2 million to $10 million;
  • Limiting negative gearing for residential property to new residential dwellings from 1 July 2027 (subject to transitional rules); and
  • Introducing the Working Australians Tax Offset from 1 July 2027, and the $1,000 instant tax deduction for work-related expenses from 1 July 2026.

After a round of consultation, the Government has also announced further proposed measures, broadly including (among others):

  • A new targeted CGT discount for investors in innovative start-ups;
  • Barring SMSFs from utilising future limited recourse borrowing arrangements (‘LRBAs’) to acquire residential property; and
  • Exempting income of discretionary testamentary trusts from the minimum tax proposed for trusts.


Changes to car thresholds from 1 July 2026

The car limit for the 2027 income year is $69,883.

This is the highest value that a taxpayer can use to calculate depreciation on a car where they use the car for work or business purposes (and they first use or lease the car in the 2027 income year).

The maximum GST credit that can generally be claimed for the creditable acquisition of a car above the limit is $6,353 (i.e., one-eleventh of $69,883).

The luxury car tax (‘LCT’) threshold for the 2027 income year is $91,661 for fuel-efficient vehicles, and $80,809 for all other luxury vehicles.

What’s new for Small Business? 

The ATO is reminding business taxpayers of recent changes they should keep in mind this Tax Time, including the following:

  • From 1 July 2026, Payday Super applies. Employers will need to pay super to an employee’s nominated super fund each payday, and it must reach the fund within 7 business days after payday (unless a longer timeframe applies, such as for new employees).
    Employers must also report both qualifying earnings and super liability through Single Touch Payroll (‘STP’) reporting.
    If super is not received by the fund, in full and on time, the super guarantee charge applies.
  • Businesses with an aggregated turnover of less than $10 million may be able to immediately deduct the business portion of eligible assets costing less than $20,000, where the asset was first used or installed ready for use between 1 July 2025 and 30 June 2026.
  • Businesses cannot claim a deduction for general interest charge (‘GIC’) or shortfall interest charge (‘SIC’) incurred from the 2025/26 income year.
  • From 1 April 2025 (i.e., from the 2026 FBT year), plug-in hybrid electric vehicles are no longer treated as zero or low emissions vehicles for the purposes of the FBT exemption.

Fuel excise relief extended for July

The Government has announced a further temporary extension of fuel excise relief for July, together with a reduction in the Heavy Vehicle Road User Charge.

The Government says these measures will make petrol and diesel 16 cents per litre cheaper than they otherwise would have been during July.

Check for ATO-held super

The ATO is reminding taxpayers that they may have superannuation money held by the ATO. This can include:

  • unclaimed super money received from super funds (for example, inactive low-balance accounts);
  • employer super guarantee amounts that could not be paid to a fund; and
  • certain government super contributions.

Taxpayers can check for ATO-held super through myGov, ATO online services or the ATO app.

ATO app alerts and super verification

The ATO has added an extra verification step for super transfer and consolidation requests made through the ATO’s online services.
This step is the latest ATO app security feature that helps protect against fraudulent activity.

If a taxpayer has registered their device using the ATO app, they will need to verify requests to transfer or consolidate super before the request is submitted (from May 2026).

Editor: The ATO has also advised that, on 5 June 2026, a large number of ATO messages were sent about changes to bank account details. The ATO notes that these messages were caused by a planned internal system update, and no action is required because of that message alone.
The ATO nonetheless recommends that taxpayers review any real-time ATO app alerts, check their details, and act quickly if something looks wrong.

Dental clinic liable for super guarantee charge

The Administrative Review Tribunal (‘ART’) recently considered whether an oral health therapist engaged by a dental clinic was an ’employee’ for super guarantee purposes.

The clinic argued that the therapist was not an employee but was instead an independent contractor and, as such, the clinic was not liable for the super guarantee charge.

The ART disagreed, and held that the therapist was an employee under the extended definition.

Editor: The extended definition of ’employee’ for these purposes includes a person who works under a contract that is wholly or principally for the labour of the person.
In particular, the ART found that:

  • the contract contained features consistent with an ’employment’ arrangement;
  • the therapist was part of a regulated profession and could not practise independently;
  • the purpose of the contract was to engage the therapist personally to work as a member of an integrated team (rather than to provide her with the use of the clinic and its facilities for a fee);
  • the clinic did not establish that she had a genuine right to delegate/subcontract her work; and
  • the therapist was not directly rewarded for her services, as her remuneration was subject to adjustments applied by the clinic on patient invoices.

Please note: Many of the comments in this publication are general in nature and anyone intending to apply the information to practical circumstances should seek professional advice to independently verify their interpretation and the information’s applicability to their particular circumstances.

Open Hours

Monday to Friday
8:00am to 5:00pm

Closed Public Holidays

Contact Us

27 Welsford Street
Shepparton, VIC 3630

T: (03) 5833 3000
F: (03) 5831 2988
Email Us

Transport Sector Update 2026-2027

Transport Sector Update 2026-2027

Transport Sector Update 2026-2027

transport truck

Reasonable Travel Allowance Expense Claims Update for 2026-2027

The ATO has released Taxation Determinations for 2026-2027. You can view these rates on the ATO website here.

Reasonable travel allowance claims for employee truck drivers in 2026-2027 is:

  • $32.25 for Breakfast
  • $36.80 for Lunch
  • $63.45 for Dinner

Long Distance Driver Update

Road Transport (Long Distance Operations) updated rates for 2026-2027 as of first full pay period in July are:

Grade Minimum Weekly Pay Rate Minimum Hourly Drive Rate Minimum Cents Per Kilometre
1      
2      
3             $1,057.60                   $41.25  $            0.5500
4             $1,076.20                   $41.97  $            0.5596
5             $1,089.60                   $42.49  $            0.5666
6             $1,102.00                   $42.98  $            0.5730
7             $1,118.00                   $43.60  $            0.5814
8             $1,150.50                   $44.87  $            0.5983
9             $1,169.70                   $45.62  $            0.6083
10             $1,198.80                   $46.75  $            0.6234

Major rest break allowance payable when a driver sleeps overnight in a truck has increased to $57.80 for 2026-2027.

For more information visit the Fair Work website here.

Road Transport and Distribution Updates

The updated rates for the Road Transport and Distribution Award for 2026-2027 are:

Employee classification Minimum Weekly Pay Rate Minimum Hourly Rate
Transport Worker Grade 1 $1,021.00 $26.87
Transport Worker Grade 2 $1,045.50 $27.51
Transport Worker Grade 3 $1,057.60 $27.83
Transport Worker Grade 4 $1,076.20 $28.32
Transport Worker Grade 5 $1,089.60 $28.67
Transport Worker Grade 6 $1,102.00 $29.00
Transport Worker Grade 7 $1,118.00 $29.42
Transport Worker Grade 8 $1,150.50 $30.28
Transport Worker Grade 9 $1,169.70 $30.78
Transport Worker Grade 10 $1,198.80 $31.55

For more information visit the Fair Work Website here.

Need more help or information?

Click the link below to contact us at Plus 1.

Open Hours

Monday to Friday
8:00am to 5:00pm

Closed Public Holidays
Contact Us

27 Welsford Street
Shepparton, VIC 3630

T: (03) 5833 3000
F: (03) 5831 2988
Email Us